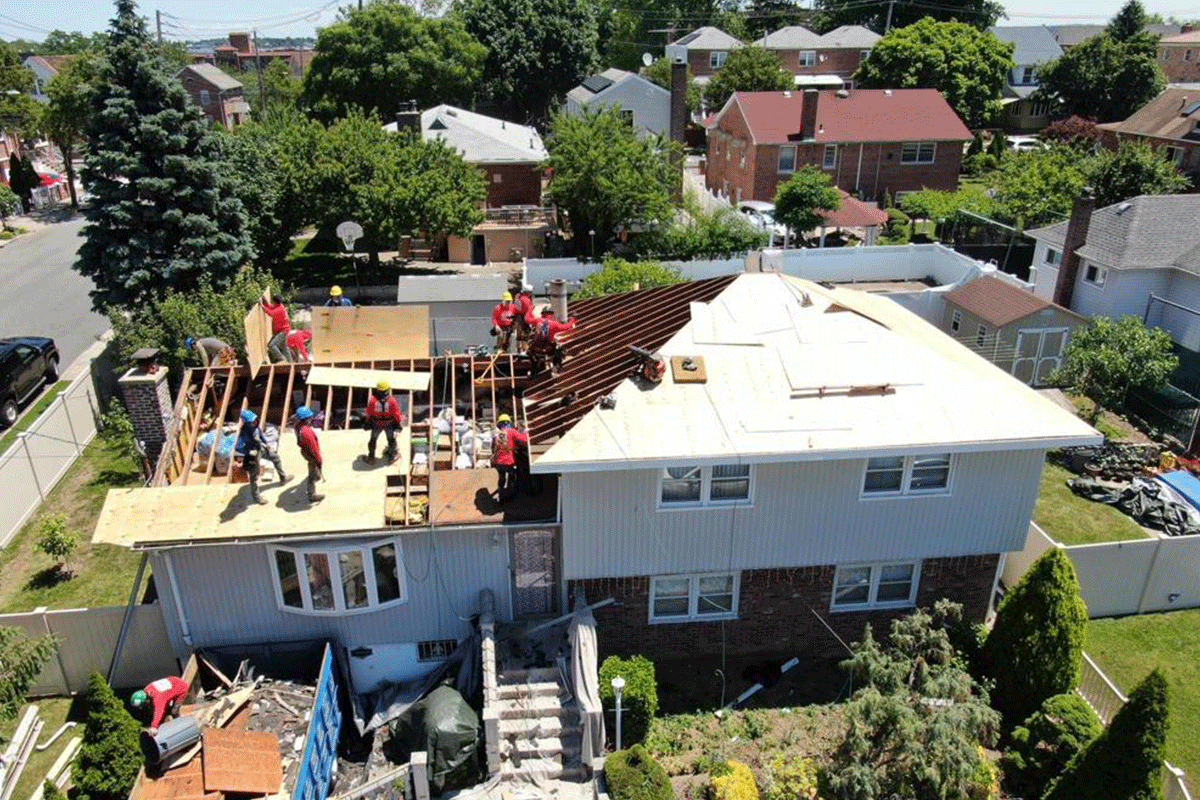
A roof in need of resort can be a nerve-wracking situation for any householder, but if the is caused by a drenched event like a surprise, hail, or fire your householder’s insurance may help cover the cost. However, navigating the policy claims work on can be . Understanding how roof resort policy claims work can help you make wise to decisions and insure that you re fully covered.
Here s a breakdown of everything you need to know about roof repair insurance claims.
1. Understanding Your Homeowner s Insurance Policy
The first step in filing a roof repair policy take is sympathy your homeowner s insurance policy insurance. Not all types of roof damage are drenched in under monetary standard policies, so it s crucial to read through the inside information of your specific plan.
What s Typically Covered?
-
Weather-related damage: Storms, hail, wind, and other natural disasters often cause roof damage that is wrapped by insurance.
-
Fire : If a fire indemnity your roof, it is usually crusty.
-
Fallen trees or junk: A tree descending onto your roof in a surprise is typically thickspread.
What s Not Covered?
-
Wear and tear: Damage from age or lack of sustenance is in the main not smothered.
-
Cosmetic : Small dents, scratches, or issues that don’t affect the roof’s function may not be spattered.
-
Negligence: If the was caused by neglect or loser to exert your roof, your claim may be denied.
It s requisite to review your insurance with your policy supplier so you can full empathize what s cloaked and what s not.
2. Document the Damage Thoroughly
Before you file a take, thoroughly the roof . This will be crucial for your policy take and could help speed up the work.
Here s what to do:
-
Take photographs: Get , detailed photos of the , both close-up and from a outdistance. If you can, try to take pictures from the run aground to avoid further damage or accidents.
-
Make a list: Write down all the disreputable areas. Be particular about what you see whether it’s missing herpes zoster, leaks, or biological science .
-
Record the date: Note the date of the incident(such as when the storm occurred) and when you first detected the damage.
This support will do as evidence when with both your policy provider and roofing .
3. Contact Your Insurance Company
Once you’ve referenced the damage, it s time to contact your insurance policy companion. Notify them of the damage as soon as possible. Insurance companies often have a specific time couc within which you must describe , so don t delay.
What You Should Expect:
-
Initial judgement: An claim agent will typically be sent out to assess the . They may travel to your home to visit the roof, take photos, and evaluate the extent of the damage.
-
Estimate of repairs: After the review, the adjuster will determine whether the is wrapped by your insurance and provide an judge of the resort cost.
Be equipped to answer any questions about the incident, such as how the occurred, when it occurred, and if you ve made temporary worker repairs(such as covering leaks with a tarp).
4. Get Multiple Repair Estimates
After your policy accompany has provided an underestimate, it s a good idea to get octuple estimates from honourable roofing contractors. This ensures that you re getting a fair damage for the repairs and that the insurance keep company s underestimate is philosophical doctrine.
When choosing a contractor, make sure to:
-
Verify their certificate: Check that the is accredited and insured.
-
Review references: Look at customer reviews and ask for recommendations from friends or syndicate.
-
Check for experience: Ensure they have go through with insurance claims and sympathize the work.
Once you have a few estimates, cater them to your policy keep company. In some cases, the policy provider may be willing to correct their first volunteer supported on these estimates.
5. Understand Your Deductible
Before receiving a payout for your roof replacement , you’ll need to empathize your deductible. The is the come you ll need to pay out-of-pocket before your insurance policy coverage kicks in.
For example, if your deductible is 1,000 and the cost of repairs is 7,000, your insurance will only pay 6,000.
Deductibles vary supported on your insurance and can depend on the age of your roof or the type of damage. Be sure to factor out this into your budgeting for repairs.
6. Work with Your Roofing Contractor on Insurance Communication
Once your exact is authorised and you’re prepare to go forward with repairs, your can help facilitate between you and your policy companion. Some roofing companies even wield the paperwork on your behalf, ensuring that all estimates and documents are submitted correctly and in a timely manner.
They can also help any discrepancies between your insurance firm s overestimate and their own, possibly serving you secure a higher payout if necessary.
7. Be Aware of Depreciation and Actual Cash Value
When with policy claims for ROOF REPAIRS, you may run into damage like wear and tear or existent cash value(ACV).
-
Depreciation refers to the loss in value of your roof over time due to age and wear. Insurance companies may subtract depreciation from the repair cost, going away you with a smaller payout.
-
Actual Cash Value(ACV) is the add up the policy companion determines your roof is Charles Frederick Worth at the time of the damage, factorisation in wear and tear.
If you have a surrogate cost policy(rather than an ACV insurance policy), the insurance payout will wrap up the full cost of replacement the roof, minus the deductible.
8. Be Prepared for Potential Disputes
It s possible that your insurance company may offer less money than you believe you re titled to, or they might deny your take birthday suit. If this happens:
-
Review your insurance policy to insure you empathize the coverage limits and exclusions.
-
Challenge the : You can appeal the take decision or request a re-inspection.
-
Consult a roofing professional: A honourable can help you tax the and supply a second view.
In some cases, you may need to involve a claims claim agent or an attorney specializing in policy disputes to ascertain a fair termination.
Conclusion
Filing a roof repair insurance exact can be overwhelming, but understanding the process and being prepared can help ease the saddle. By familiarizing yourself with your policy insurance, documenting , working with sure contractors, and wise to what to expect, you can maximize your claim and get your roof repaired with stripped try.
If you’re incertain about anything during the work on, don t hesitate to reach out to your policy federal agent or a professional person roofing contractor for direction. Your home s protection is worth it.